

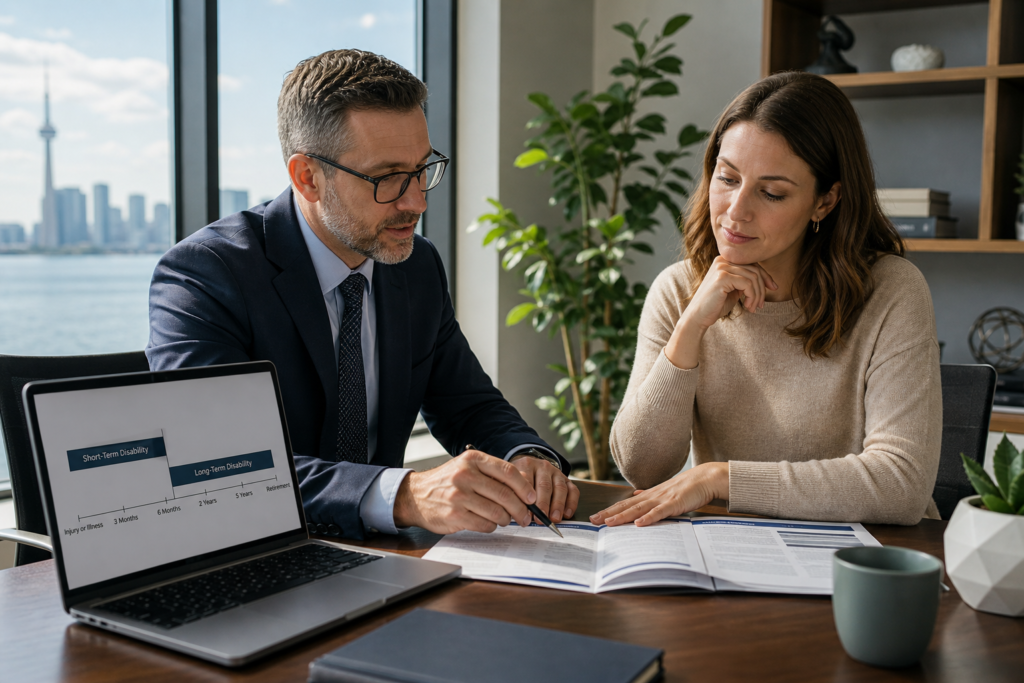
Short-term and long-term disability coverage address different stages of an illness or injury that prevents you from working. Short-term disability generally focuses on the initial period away from work, while long-term disability is designed for a potentially extended inability to earn an income.
They are not automatically interchangeable. The right choice depends on your income, savings, occupation, workplace benefits, household responsibilities, and the exact policy wording. This comparison explains how the two types of coverage may work together and what to review before comparing disability insurance in Canada.
Short-Term vs Long-Term Disability: The Essential Difference
Short-term disability coverage generally applies to the earlier stage of a disability, when a person is temporarily unable to work. Long-term disability coverage is intended to continue protecting income when the inability to work lasts beyond the short-term period, subject to eligibility requirements and benefit terms.
That basic distinction does not determine whether coverage is suitable. Policies can differ in their waiting periods, definitions of disability, benefit periods, exclusions, offsets, taxation, medical evidence requirements, and treatment of partial work. A policy that appears affordable may provide less useful protection if its definition does not match your occupation or other benefits reduce the amount payable.
Jubilee Financials provides disability income protection guidance as part of its insurance advisory services. It serves clients across Canada from Ontario. This article is general education, not individualized insurance, legal, or tax advice.
Short-Term and Long-Term Disability Compared

The table describes common design patterns rather than universal rules. The actual contract, certificate, application, and insurer claims requirements control the coverage.
| Criterion | Short-term disability | Long-term disability |
|---|---|---|
| Purpose | Addresses income loss during the earlier period of an illness or injury. | Addresses income loss when inability to work continues for a longer period. |
| Payment start | Begins after a policy-specific waiting period and eligibility assessment. | Usually begins after a longer elimination period, often following short-term benefits. |
| Duration | Designed for a limited period. | Designed for a longer period, subject to continuing eligibility. |
| Disability definition | May use a regular-occupation or other policy standard. | May begin with one definition and later change to another. The wording must be confirmed. |
| Benefit amount | Set by the plan or policy and may be limited by income or coordination rules. | May be reduced by other income sources or policy offsets. |
| Main tradeoff | May help with immediate cash flow but not a prolonged absence. | May address a longer risk but not the initial waiting period. |
| Review risk | A gap may arise before long-term benefits begin. | Eligibility may depend on a narrower definition, ongoing evidence, or a limited benefit period. |
Why timing matters
A person can have long-term coverage and still face an immediate income problem if benefits do not begin at once. Conversely, short-term coverage may help with early expenses but end before a serious condition has resolved. The question is whether your protection matches the full timeline of a possible income interruption.
Why definitions matter more than labels
“Short-term” and “long-term” describe the intended period of coverage, but they do not explain eligibility. A policy may assess whether you can perform your own occupation, regular occupation, any occupation for which you may be suited, or another standard stated in the contract.
Ask for an explanation based on your actual duties. A desk-based professional, tradesperson, business owner, and health-care worker may experience very different consequences from restrictions on lifting, standing, travelling, concentrating, or using specific skills.
How Short-Term and Long-Term Benefits May Work Together
The two types of benefits may form a sequence rather than competing choices. An employer plan or personal policy may provide short-term benefits first, followed by long-term benefits if the disability continues and the claimant meets the next stage of the contract. Other arrangements may offer only one type of protection.
The transition is not necessarily automatic. You may need to submit another claim form, provide updated medical information, meet a continuing definition, or comply with a deadline. Approval for short-term benefits is not automatically a guarantee that long-term benefits will be approved.
Where gaps can occur
- Waiting-period gap: Long-term benefits may not pay until a specified period has passed, while short-term benefits may end earlier.
- Definition gap: The long-term test may differ from the short-term test.
- Documentation gap: Medical information or claim forms may need updating during the transition.
- Coordination gap: Another benefit may reduce the amount payable.
- Employment gap: Workplace coverage may depend on active employment, plan membership, or portability.
Draw the timeline on paper. Record when savings could be used, when workplace benefits might begin and end, when a personal policy could respond, and what evidence is required. This can reveal a gap that is not obvious from the policy name or headline benefit amount.
The Criteria That Should Drive Your Decision
The most suitable balance depends on the financial risk created by an inability to work. Start with these criteria instead of beginning with a premium quote.
Emergency savings and essential expenses
List housing, food, utilities, debt payments, transportation, medication, child care, and other costs that would continue during a work absence. Do not count every asset as immediately available. Consider how quickly you could access it and whether doing so would create another financial problem.
A larger emergency reserve may make a longer waiting period more manageable, but it does not remove the risk of a prolonged disability. A smaller reserve may make early income protection especially important, although affordability still needs to be assessed.
Household dependence on your income
Two households with the same salary may need different protection. One may have a second stable income and few debts. Another may depend almost entirely on one person’s earnings, have young children, or support relatives. Include a spouse’s or partner’s income only if it is reliable during a disability.
Occupation and work duties
Consider the physical, cognitive, emotional, and technical demands of your job. A policy definition that seems reasonable in general may not match the consequences of losing the ability to travel, lift, concentrate, operate equipment, or perform a specialized task.
Existing workplace coverage
Obtain the full benefits booklet or plan certificate. Identify the benefit amount, waiting period, maximum duration, disability definition, offsets, exclusions, taxation treatment, claim process, and rules that apply if you leave the employer. A summary from human resources may be useful, but it should not replace the governing documents.
Partial disability
Some conditions do not prevent every form of work. You might work fewer hours, accept modified duties, or earn less while still incurring substantial expenses. Ask whether the policy addresses residual, partial, or recurrent disability and how reduced earnings are assessed.
Affordability and suitability
Affordability is not merely the lowest monthly price. A cheaper policy may have a longer waiting period, shorter benefit period, narrower definition, more exclusions, or greater uncertainty about coordination. Compare the protection provided during the risks that matter most, then decide whether the premium fits your budget.
If You Are an Employee
Employees should review workplace disability coverage before assuming they need separate insurance or that the employer plan is sufficient. Employer benefits may be valuable, but the benefit amount and wording determine how much protection they actually provide.
- Is the coverage short-term, long-term, or both?
- What income is used to calculate the benefit, and is there a maximum?
- What waiting period applies to each benefit?
- What definition applies at the start and later in the claim?
- Are bonuses, commissions, overtime, or other income included?
- Are benefits reduced by other income sources?
- What exclusions, medical requirements, and deadlines apply?
- What happens if you change jobs, take leave, reduce hours, or become self-employed?
Personal coverage may be worth reviewing when workplace benefits do not reflect your income, occupation, household responsibilities, or desired benefit period. It may also matter if the workplace plan is not portable. Do not compare only the stated percentage of income. A higher percentage may still provide less practical protection if the maximum is low or offsets reduce the payment.
If You Are Self-Employed
Self-employed workers often need to examine disability protection without relying on an employer-sponsored plan. The financial impact may include personal living costs, business overhead, client obligations, and the cost of hiring someone during an absence.
Separate personal income protection from business continuity planning. A personal disability policy may replace part of your earnings. It may not automatically pay business expenses, compensate for lost contracts, fund a replacement worker, or protect a business partner.
Calculate household needs separately from business expenses. Consider how long savings could support both. Ask about the waiting period, benefit amount, occupation definition, and partial-disability provisions. A self-employed person may complete some tasks but lose the ability to handle sales, travel, manual work, or client meetings.
If You Own a Small Business
Small-business owners should review three exposures: personal income, the business’s reliance on a particular person, and the financial effect of a prolonged interruption. These exposures overlap but are not identical.
Ask what would happen if you could not perform your usual role. Could another employee take over? Would revenue continue? Would the business need financing? Would a partner have the authority and resources to manage operations? The answers can guide continuity planning, but they do not determine insurance eligibility.
Policy ownership, premium payment, beneficiaries, benefit recipients, and tax treatment can have important consequences. The appropriate treatment depends on the policy, business structure, and circumstances. Obtain advice from qualified insurance, legal, and tax professionals before acting on a business arrangement.
Disability Policy Review Checklist
Use this checklist for workplace documents or personal policies. Every item requires confirmation in the actual contract.
Definition of disability
Ask whether the policy uses an own-occupation, regular-occupation, any-occupation, or another definition. Confirm whether the definition changes after a period of benefits and how the insurer assesses duties, earnings, transferable skills, and modified work.
Waiting period
Confirm how long you must be disabled before benefits may begin and how the period is measured. Ask whether sick leave, vacation, short-term benefits, or other income count toward it. Check how recurrent disability is treated.
Benefit period and termination
Identify how long benefits may continue if eligibility remains established. Confirm the events that can end benefits, including recovery, a change in definition, reaching a stated age, returning to work, or failing to provide evidence.
Residual or partial disability
Ask whether benefits apply when you can work but experience reduced hours, duties, or earnings. Find out how the loss is measured and whether partial benefits can continue after a full disability claim.
Exclusions and limitations
Request an explanation of exclusions, pre-existing-condition provisions, travel-related conditions, mental-health provisions, substance-related exclusions, and occupation-specific restrictions. Do not assume a limitation applies or does not apply without reading the wording.
Offsets and coordination
Ask which other income sources may reduce the benefit. Clarify how workplace benefits, pensions, accident benefits, or other disability coverage are treated. Several plans do not necessarily mean receiving the full amount from each one.
Renewability, premiums, and claims
Determine whether premiums can change and whether the insurer can cancel or alter coverage. Ask what happens if your occupation or income changes. Also ask what medical records, employer statements, financial records, functional assessments, and ongoing updates may be required during a claim.
How Workplace and Other Benefits May Affect the Review
Before comparing personal coverage, map every possible income source during a disability. Include employer-sponsored plans, paid leave, personal insurance, savings, household income, and other relevant sources. This is an inventory, not a prediction that you will qualify for each one.
Coordination provisions can change the amount payable. Some benefits may be reduced when another source applies, while other sources have separate eligibility rules. Government programs, employment benefits, provincial supports, and tax rules can change and may depend on individual circumstances. Confirm current requirements through the appropriate official source or qualified professional.
Questions to Ask Before Comparing Quotes
Bring workplace documents, income information, occupation details, current insurance, monthly essential expenses, savings estimates, and questions about existing exclusions.
- How much essential monthly income should I consider protecting?
- What disability definition applies to my occupation?
- How would the coverage address partial or recurrent disability?
- What waiting period fits my savings and workplace benefits?
- How long could benefits continue?
- What exclusions, limitations, or underwriting issues should I understand?
- Which benefits could offset the amount payable?
- How would the proposed policy coordinate with existing coverage?
- What information would be required during a claim?
- Can premiums change if my occupation or income changes?
- Who can help explain the policy and claims process?
Jubilee Financials describes its approach as personalized and needs-based, with comparisons from multiple Canadian insurers and claims support. Its advisory approach can help readers assess what type of service they want from an advisor.
A Practical Way to Review Your Existing Protection
Begin with documents, not assumptions. Collect your workplace benefits booklet, personal policy contracts, recent income information, and correspondence explaining current coverage. Highlight the benefit amount, waiting period, disability definition, benefit period, exclusions, offsets, and claim instructions.
Next, calculate minimum household income needs. Separate essential expenses from discretionary spending, then consider debts, dependants, medical costs, and expenses that may increase during an illness or injury. Note how much savings could realistically be used and for how long.
Then compare the coverage timeline. Identify what could pay during the first stage, when that support could end, and when long-term coverage could potentially begin. Write down every unclear period. An unanswered question is a reason to seek clarification, not a reason to assume the policy will respond.
Finally, compare contract terms across options. Look beyond premiums to definitions, partial-disability provisions, exclusions, offsets, renewability, benefit periods, and claims requirements. If coverage involves a business, include appropriate legal and tax professionals.
Jubilee Financials LTD is an Ontario-based insurance advisory located in Ottawa and serving clients across Canada. The firm offers personalized disability income protection guidance, comparisons from multiple Canadian insurers, and claims support. You can request a quote from Jubilee Financials for an individualized discussion.
Short-Term and Long-Term Disability FAQ
Are short-term and long-term disability insurance alternatives?
They can work together when the policies cover different stages of the same income interruption. Short-term coverage may address the initial period, while long-term coverage may begin later if the disability continues. Waiting periods, definitions, and claim requirements must be confirmed in the actual documents.
Is workplace disability coverage enough?
It may be enough for some people, but the existence of a workplace plan does not answer that question. Review the benefit amount, maximum, waiting period, definition, duration, offsets, exclusions, taxation, and portability. Compare those terms with essential income needs and occupation.
When should a self-employed person review disability coverage?
Review it whenever income, occupation, business responsibilities, household obligations, or existing benefits change. Distinguish personal living expenses from business expenses and consider how long savings could support both. Pay particular attention to partial disability.
What should I check before requesting a quote?
Identify your income need, occupation, savings, workplace coverage, and household responsibilities. Then ask about the disability definition, waiting period, benefit period, partial disability, exclusions, offsets, taxation, renewability, premium changes, and claims documentation.
Choosing the Right Disability Coverage Review
Short-term and long-term disability coverage address different parts of the income protection problem. Short-term benefits may help with immediate cash-flow pressure, while long-term benefits may matter when an inability to work continues. Whether you need one, both, or a review of workplace protection depends on your savings, income, occupation, household responsibilities, and policy wording.
Gather your documents, calculate essential expenses, examine definitions and offsets, and ask how coverage would respond to full, partial, and prolonged inability to work. If you are self-employed or own a business, review personal income protection separately from business continuity.
Jubilee Financials LTD serves individuals, families, and small businesses across Canada from Ontario, offering personalized advice, comparisons from multiple Canadian insurers, and claims support. Contact Jubilee Financials to discuss your disability income protection review.